Intelligence, uncertainty and decision-making in commercial property
I have spent almost twenty years in commercial real estate in Romania — first as Deputy Manager at Atlas Management Company, a fund listed in London and Warsaw, and since 2010 as Country Manager for Jupiter Group Romania, a private investment group with roots in Israel and a track record spanning three continents.
My role covers everything a Country Manager in a family office context tends to cover: strategy, leasing, tenant relations, financing, development oversight, asset sales and Board-level reporting. We own and manage office buildings in the Bucharest central business district, including heritage properties with complex histories, we have developed and sold a large shopping center, and have active residential and mixed-use projects in the pipeline.
It is not a simple job to describe, which is part of why I have enjoyed it. Real estate at this level is not any more only about buildings. It is about understanding people, organizations, markets and governments well enough to decide on incomplete information. You sign leases with companies whose finances you cannot fully audit, invest in locations whose regulatory future is uncertain, and negotiate with people who will not tell you what they actually think. Every transaction is, in some sense, an intelligence problem.
I did not have that framing when I enrolled in the Business Intelligence MBA at Bucharest Business School in 2023. I enrolled out of curiosity, and because after two decades of deciding largely by instinct I wanted to know whether a more rigorous logic sat underneath it.
MBI, an unexpectedly coherent hybrid
The programme was built jointly by ASE’s Faculty of Business Administration in Foreign Languages and the “Mihai Viteazul” National Intelligence Academy. It ran through Economic War Theory, National Intelligence Systems, Data Collection, Cybersecurity and Financial Investigations, taught by intelligence practitioners and international competitive intelligence experts alongside senior Romanian economists. On paper, a curious hybrid. In the classroom, with a cohort mixing private and public sector professionals across a refreshing range of ages, it was far more coherent than I expected.
The module that reorganized my thinking was Rainer Michaeli’s course on Strategic and Competitive Intelligence. Michaeli directs the Institute for Competitive Intelligence in Germany. He began by dismantling the romance of his own subject: whatever the popular imagination attaches to the word intelligence, the work itself is structured research, disciplined source evaluation and honest reporting. Not espionage — a legal, systematic process for turning available information into something a decision-maker can act on.
The intelligence cycle — planning, collection, processing, analysis, reporting — maps almost exactly onto the decisions I make constantly. Before a major lease or an acquisition: what is the question I actually need answered? Which sources can answer it, and what is each worth? How do I separate confirmed fact from plausible rumor, and say so honestly? How do I invert my own reasoning so the Board gets the conclusion first rather than wading through my working? I had been improvising versions of this for years; the course gave it a sequence and a name.
One example has stayed with me. Michaeli showed a market assessment prepared for Daimler in 1901, concluding that global demand for automobiles would never exceed a million units, principally because there would never be enough qualified drivers. His point was not that the analysts were foolish — given the roads and technology of 1901, it was competently argued. It was about the limits of analysis under structural uncertainty: how rigorous work still fails when the analyst cannot see what will make his assumptions obsolete. For anyone forming a view on the future of the Bucharest office market, this an uncomfortably familiar problem.
A market that has been stress-tested
Commercial property in Bucharest has spent several years absorbing shocks faster than it could digest them. The pandemic reset assumptions about how much office space an organization needs and what it is for. The war in Ukraine changed the region’s perceived risk profile overnight and pushed construction costs sharply up, at the worst moment for anyone mid-development. Interest rates then repriced every income-producing asset in the market. Romania’s internal political situation adds further fuel to the fire.
What emerged is a sharply polarized market. Demand has concentrated in well-located, energy-efficient buildings while secondary stock struggles at any price. Tenants arrive far better informed than five years ago, think in cost per employee rather than per square meter, and will pay for quality while being ruthless about anything surplus. Leases are shorter. Landlords now compete on service and sustainability, not rent alone: energy performance shows up directly in operating costs, in financing conditions and in exit value.
Romania adds its own variable: administrative unpredictability. Anyone who has taken a complex development through permitting in Bucharest — particularly involving heritage buildings or ultra-central sites — knows the binding constraint is often not capital, design or demand. It is the ability to anticipate how institutions will behave. This is where the intelligence habit of mind earns its keep: mapping the actors, understanding their incentives, tracking precedent and building scenarios rather than betting on one expected outcome.
The opportunity in all this is that quality has become scarce. Little genuinely prime space has been added to the central business district recently, even less is expected to be delivered in coming years, and construction economics suggest little will make sense in the future. I would make a particular case for buildings with history. They are difficult — complex refurbishment, slow permitting, unforgiving engineering — but they cannot be replicated, and organizations increasingly want premises that say something about who they are. There is an environmental argument too: the most sustainable building is often the one that already exists. In Bucharest, where so much architectural inheritance has been lost, the commercial and the civic case point the same way.
What artificial intelligence actually changes
Real estate digitalized late and is catching up. Over the past two years I have used AI tools for precisely the work the intelligence cycle describes: cross-referencing information on tenants and partners, summarizing long legal and technical documents, structuring analysis, drafting Board material. They are very good at collection and processing — historically the most laborious stages — and far weaker at judgement, at knowing which question matters, and at reading the institutional dynamics that determine so much of what happens in this business. Which seems to me the right way round: if the mechanical parts of analysis become cheap, the scarce skill becomes asking the right question and reading the answer skeptically. An argument for exactly MBI’s master degree’s type of education.
Advice
Take seriously the difference between information and understanding. It has never been easier to accumulate data, but be humble because it is still very hard to know what it means. The people who advance are not those who know the most facts; they are those who can look at a confused situation, work out which two or three questions determine the outcome, find defensible answers and commit while the picture is still incomplete.
And treat curiosity as a professional asset rather than a distraction. I went back to formal study after nearly twenty years in the industry, in a field adjacent to my own, with no career objective in mind. It was among the most useful things I have done, precisely because it was not instrumental. Learning outside your own specialisation is what stops long experience from hardening into fixed assumptions — which is, after all, exactly the failure mode of those Daimler analysts.
Five books
Not management books, deliberately. The most useful reading I have done for my working life has rarely come from the business shelf.
The Cherry Orchard — Anton Chekhov. A family loses its estate because it cannot bring itself to make a property decision. Lopakhin the merchant arrives with an entirely sound proposal — subdivide the land, lease plots, service the debt — the family finds it vulgar and does nothing, and the estate is auctioned to him anyway. This play describes the most accurate thing I know about the emotional relationship owners have with property. I would put it on the reading list of anyone entering this industry. It also is about human psychology in a divisively simple Chekhovian way, and much of what I do is about this actually – the people and their responses to situations.
Geopolitical Alpha — Marko Papić. The closest thing to a practical manual for what an intelligence education teaches: forecast by mapping the constraints a decision-maker actually faces, not their stated preferences. Anyone who has waited on a planning decision will see immediately why that matters.
Living with Distrust: Morality and Cooperation in a Romanian Village — Radu Umbreș. An anthropologist on how trust, suspicion and cooperation really work in a Romanian community — something everyone doing business here navigates daily and almost nobody examines analytically. It was one of the best reads in the past years, strongly recommend it for anyone living and working in Romania.
The Economic Weapon — Nicholas Mulder. How economic pressure became an instrument of statecraft. After 2022, nobody in this region needs persuading that this belongs in a commercial risk assessment.
Spies: The Epic Intelligence War Between East and West — Calder Walton. A corrective to the popular image of the field. What emerges is how much of the work was patient collection and institutional politics — and how often good information failed to change anyone’s mind.
What I read
Daily news in newsletter and online form rather than print, across several outlets and in more than one language — the only reliable way to notice when two credible sources describe the same event incompatibly; The Economist, Financial Times, Bloomberg, The Free Press. Beyond that I read or listen widely and consistently, in ways that do not map onto my job: Romanian history and post-communist analysis, geopolitics and economic statecraft, a great deal of memoir and diaries, Russian and European classics, contemporary fiction. I read most of Chekhov this year and most of Dostoevsky a few years ago. I also religiously read our advisory firms’ market reports — indispensable, provided one remembers who commissioned them.
What I find missing in the economic media, here and elsewhere, is patience. A great deal of commentary is organized around what changed this week, very little around the slow forces that determine outcomes over the horizon on which real estate operates. The remedy is not more news. It is history, and the occasional novel.
ABOUT
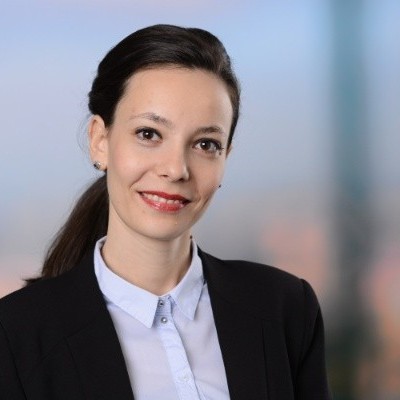
- Catinca Ciornei, Country Manager, Jupiter Group Romania, Alumni INTELLIGENCE MBA